The SAFE Stacking Trap
Every additional SAFE you sign is a withdrawal from your own equity — and most founders never run the balance.
Published: September 2026 · Desert Gate Capital Research Desk · Dubai, UAE
7-minute read · SAFE Notes · Founder Dilution · Cap Table Management
You sign the first SAFE feeling sharp. Quarter-million dollars, clean terms, no board seat, no maturity date. The second one arrives three months later at a higher cap — feels like progress. The third comes with a bigger cheque and an even bigger cap, and by now the fundraising muscle memory is so smooth that the cap table modelling has fallen behind. Then the Series A term sheet lands, and the conversion waterfall runs, and the number staring back at you is not the number you expected.
This is not a hypothetical. According to a 2026 analysis by CapWave AI, 83% of founders who stack post-money SAFEs end up with a dilution figure meaningfully larger than the one they modelled. The gap between what founders think they own and what they actually own at Series A conversion has become one of the most predictable — and most avoidable — errors in early-stage fundraising.
The Data Reality
The post-money SAFE, introduced by Y Combinator in 2018, is now the default instrument for pre-seed and early-seed fundraising. According to Carta’s 2026 data, SAFEs appear in roughly 90% of pre-seed rounds. The market has standardised around a single instrument — and most founders misunderstand the one thing it was designed to make simple.
Here is how the math works in practice. Consider a founder who raises through three consecutive SAFEs before a priced round:
| SAFE | Amount | Post-Money Cap | Ownership Locked |
| SAFE 1 | $250,000 | $5,000,000 | 5.00% |
| SAFE 2 | $500,000 | $8,000,000 | 6.25% |
| SAFE 3 | $1,000,000 | $12,000,000 | 8.33% |
| Total | $1,750,000 | 19.58% |
Source: CapWave AI, Post-Money SAFE Stacking Analysis, 2026
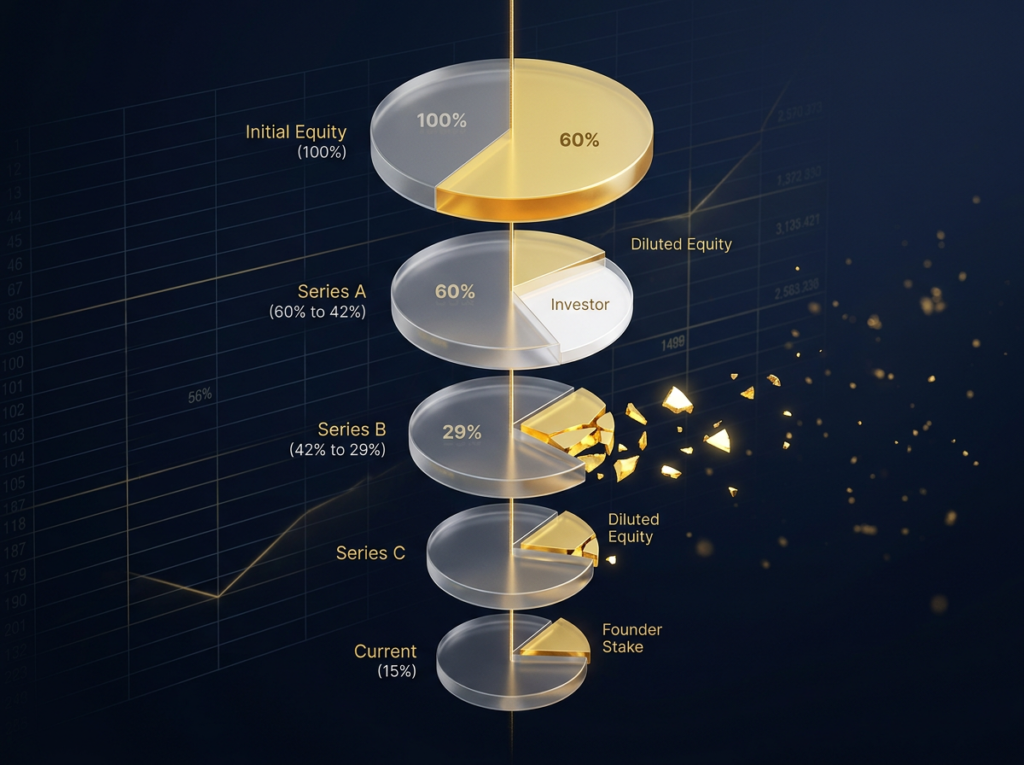
Nineteen and a half percent of the company — gone before a single priced share is issued. Add a Series A at 20% dilution and a 10–15% option pool expansion (which, in 95% of term sheets, is carved from the pre-money valuation and therefore borne by existing shareholders), and the founding team can cross below 50% ownership before the Series A cheque clears.
Carta’s 2026 Founder Ownership Report, drawing from data across 9,304 startups, puts the median founding-team ownership at 54.8% at seed stage. By Series A, that drops to 35.6%. For founders in physical industries — hardware, biotech, manufacturing — the median falls further to 30.5%. These are medians. The founders who stacked aggressively without modelling sit below them.
The valuation caps themselves add context. Non-AI startups in 2026 are seeing SAFE caps in the range of $6M–$10M at pre-seed and $10M–$15M at seed, according to Carta and CapWave data. At these valuations, a $500,000 SAFE locks in 5–8% ownership in a single instrument. Stack three of them and you are approaching the dilution of a priced seed round — without the governance, the board representation, or the signalling value that a priced round provides.
The Core Problem: Why Post-Money SAFEs Compound Against Founders
The design of the post-money SAFE is the source of the confusion. Under a pre-money SAFE, each new investor dilutes all prior SAFE holders alongside the founders. Under the post-money version — which Y Combinator introduced specifically to give investors certainty — each SAFE holder’s ownership percentage is fixed at signing. That certainty has to come from somewhere. It comes from the founders.
Every post-money SAFE you sign dilutes exactly one party: you. SAFE 2 does not dilute SAFE 1. SAFE 3 does not dilute SAFE 2. The entire incremental cost of each new instrument lands on the founding team’s cap table line. This is not a flaw in the instrument. It is the instrument’s explicit design. But it produces a compounding effect that most founders do not model until conversion forces them to.
Three specific errors drive the gap between expected and actual dilution:
First, founders treat each SAFE in isolation. They calculate SAFE 1 as 5%, SAFE 2 as 6.25%, and SAFE 3 as 8.33%, then mentally sum them to roughly 19.6%. The real number may differ when MFN clauses, discount rates, or pro-rata side letters interact with the conversion waterfall. Founders who round down at each step and then round down again on the total can be off by two to three percentage points.
Second, founders forget the option pool shuffle. Institutional Series A investors — almost without exception — require the option pool to be created or expanded before their money prices in. A 12% new pool on a $10M pre-money round dilutes founders by roughly 12 points on top of the ~20% for the round itself. Founders who modelled their post-SAFE ownership without including the pool hit a second surprise at the term sheet stage.
Third, founders miscalculate the pro-rata overhang. Most post-money SAFEs include optional pro-rata rights, giving each SAFE holder the right to invest in the Series A to maintain their ownership. When ten angel investors each exercise pro-rata, the total allocation to existing holders can consume 10–15% of the round before the new lead investor’s cheque is counted. This constrains round sizing, irritates lead investors, and further compresses what is available for the founders.
The Institutional Lens
From an investor’s seat, the picture looks different — and understanding that difference is part of solving the problem.
A Series A lead examining a cap table wants to see two things: that the founders have enough ownership to stay motivated through the next three to five years of value creation, and that the cap table is clean enough to not create governance headaches. Both of these break down when SAFEs have been stacked without planning.
When Carta reports that median founding-team ownership at Series A is 35.6%, that figure includes the option pool and all prior dilution. Institutional investors set informal floors. A founding team below 50% before the Series A closes raises a flag. Below 40% raises a conversation. Below 30% can stall a deal entirely — not because the investor objects morally, but because the incentive alignment starts to deteriorate.
A founder who owns 25% of a company priced at $40M has $10M in paper value, which sounds significant until you account for the four-year grind to Series B and the liquidation preferences stacking above them.
Fund managers also pay attention to SAFE cap escalation. A cap that jumps from $5M to $8M to $12M across three instruments — without a corresponding change in the company’s metrics — signals pricing indiscipline. It suggests the founder raised each SAFE at whatever cap the market would bear, rather than calibrating to actual progress. That pattern, visible in the cap table, quietly undermines the founder’s negotiating position when the priced round arrives.
The Cap Table Hygiene Protocol: A Six-Stage Framework
Avoiding the stacking trap does not require avoiding SAFEs. It requires treating every SAFE as a cap table event — not a casual transaction.
Stage 1 — Set a Dilution Budget Before You Raise Anything
Before signing the first SAFE, determine the maximum pre-Series A dilution you are willing to accept. Best practice: cap total SAFE dilution at 15–20% of the company. Write this number down and revisit it before every new instrument.
Stage 2 — Model the Full Conversion Waterfall Before Each New SAFE
Do not sign a second SAFE without running the conversion waterfall for all existing SAFEs plus the proposed one. Include the anticipated Series A dilution (typically 15–25%) and option pool expansion (10–15%) in the model. The output should show your projected ownership post-Series A — not just post-SAFE.
Stage 3 — Anchor Valuation Caps to Milestones, Not Market Mood
Each increase in cap should correspond to a measurable change in the company: revenue, users, contracts, partnerships, technical milestones. If you cannot articulate why the new cap is higher than the last one, the cap is probably too high — and an aggressive cap today means a harder Series A valuation conversation tomorrow.
Stage 4 — Consolidate When Possible
Rather than stacking three SAFEs at three different caps over six months, consider a single SAFE round with a defined close window. One instrument, one cap, one conversion event. This simplifies the cap table and gives you more control over total dilution.
Stage 5 — Negotiate Pro-Rata Rights Carefully
Pro-rata rights are not free. Every pro-rata commitment you make to a SAFE holder is capacity you are reserving in your Series A for a small cheque. Limit pro-rata rights to your largest SAFE investors or offer them as major-investor side letters rather than default terms.
Stage 6 — Share the Cap Table With Your Lead Investor Early
Do not wait until the term sheet to show the conversion waterfall. Share a clean cap table model with your prospective Series A lead during diligence. Surprises in the cap table kill deals. Transparency accelerates them.
The post-money SAFE did exactly what Y Combinator designed it to do: it gave investors certainty. That certainty is purchased with founder equity, one instrument at a time, in increments small enough to feel painless and large enough to compound into a serious problem.
The 83% of founders who get this math wrong are not careless. They are busy — building product, hiring, selling — and the cap table is a spreadsheet they will update later. Later arrives at the Series A term sheet, and by then the numbers are fixed.
The instrument is not the enemy. The absence of a model is.